Scaffolding and temporary structures insurance
Scaffolding, shoring, concrete forms and site trailers move from job to job like any other equipment, and they can be stolen, blown over or crushed the same way.
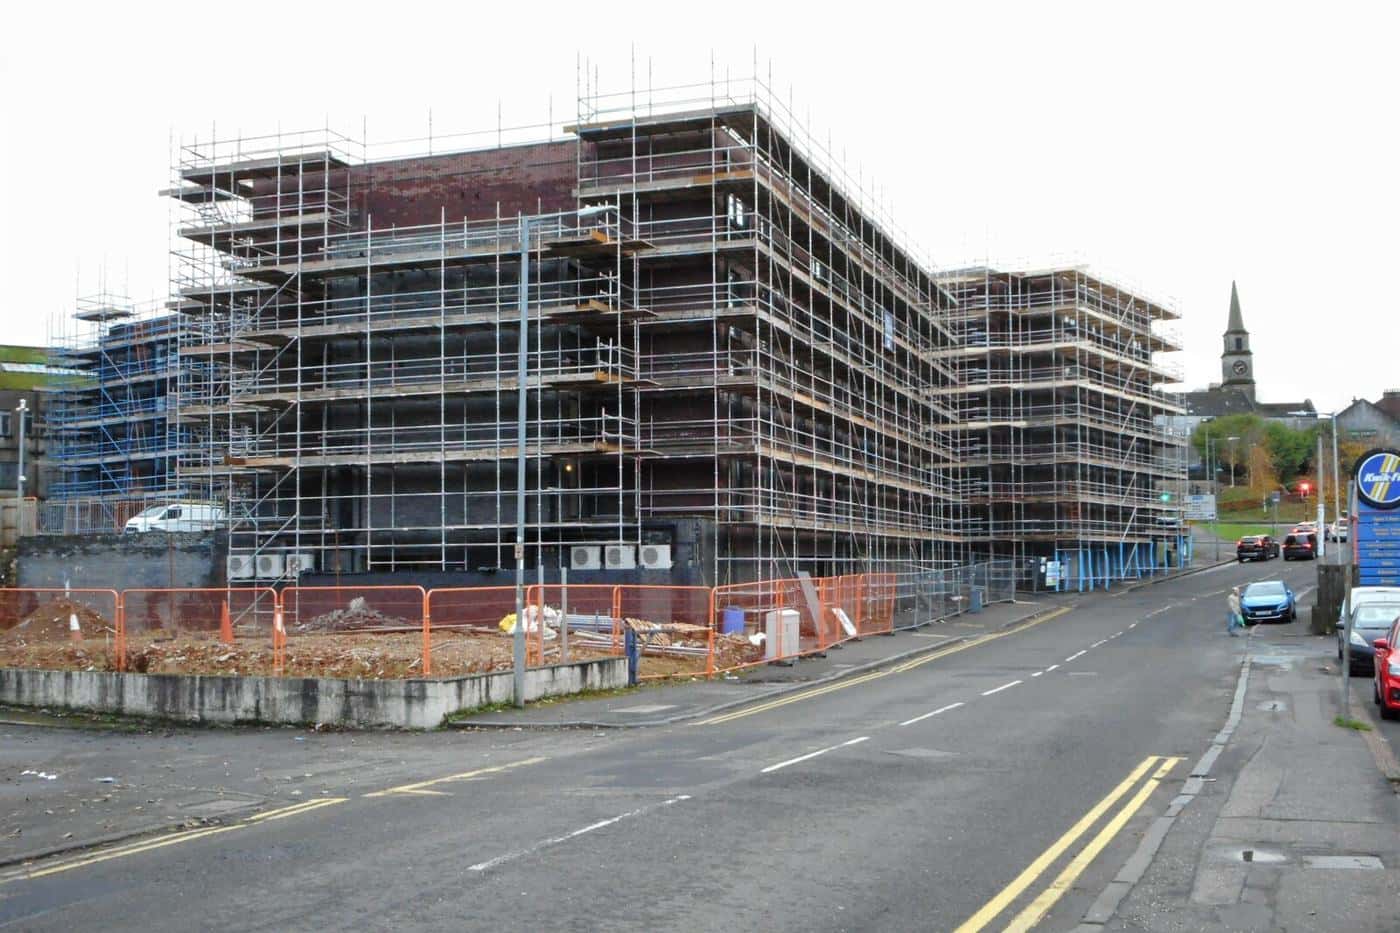
What can be covered
- Owned frame, tube-and-clamp and system scaffolding
- Shoring and concrete forming systems
- Construction fencing, barricades and temporary signage
- Job-site office trailers and storage containers, and their contents
Apply online
The online application asks the questions underwriters need for this coverage. Business owners fill it out directly, and insurance agents can complete it for a client or send it to them. Insurance agents can also request an appointment.
Contractors equipment or builders risk
Scaffolding you own goes on your contractors equipment policy, usually under the blanket limit or as a scheduled total. A project builders risk policy sometimes includes temporary structures, but usually only for that project and often with a low sub-limit.
If you rent scaffolding to others
Scaffold rental and erection companies have a liability exposure beyond the equipment itself. If renting or erecting scaffolding is your main business, see the equipment rental business page for the liability side.
Common losses and gaps to ask about
Theft of components
Frames, braces, planks and couplers are easy to load and sell for scrap. Losses are often found only at inventory, so ask whether the policy excludes unexplained shortages or mysterious disappearance.
Wind and collapse
Scaffolding wrapped in netting or sheeting can catch wind like a sail. Ask whether collapse is covered and whether a windstorm deductible applies in your area.
Wear, rust and bent parts
Gradual wear and corrosion are usually excluded. Damage from a single event, such as a truck backing into a scaffold, is the kind of loss these policies are meant to cover.
How to list scaffolding and temporary structures
- Count your scaffolding by type: frame, tube-and-clamp and system, plus shoring and forms.
- Put a replacement value on each group, using recent purchase invoices where you have them.
- List site trailers and storage containers separately, with year, make, serial number and value.
- Estimate the value of contents kept in trailers, such as plans, computers and small tools.
- Note where idle stock is stored and how the yard is secured.
- Decide whether to schedule high-value items or cover them under a blanket limit, and confirm the blanket per-item cap.
Common questions
Is scaffolding covered under my blanket equipment limit?
It can be, but a full scaffolding inventory often exceeds a typical blanket limit. List the total value on the application so the limit is set correctly.
Are job-site trailers covered on the road?
The trailer as property can usually be covered on an equipment policy, including in transit, depending on the form. Liability for towing it on public roads belongs on your commercial auto policy.
Does it cover scaffolding I rent from someone else?
Rented scaffolding usually needs rented equipment coverage, which many contractors equipment policies offer as an extension with its own limit. Check the rental contract, since it may make you responsible for the full value.
Need a contractor license bond?
Many states and cities require a contractor license bond before you can get licensed or pull permits. Find the bond your state requires.
Ready for a quote?
One online application. Owners and agents both welcome.
Start the contractors equipment applicationRelated coverage
Owned Equipment
Scheduled or blanket coverage for the machines and attachments you own or finance.
Coverage & applicationBuilders Risk
Covers the building while it goes up: framing, materials on site and in transit, through completion.
Coverage & applicationEquipment Rental Business
Rental yards renting tools, lifts, light towers and heavy equipment to contractors and homeowners.
Coverage & applicationContractors Tools
Hand and power tools on the truck, in the gang box, and at the job site.
Coverage & application