Medical, diagnostic and scientific equipment insurance
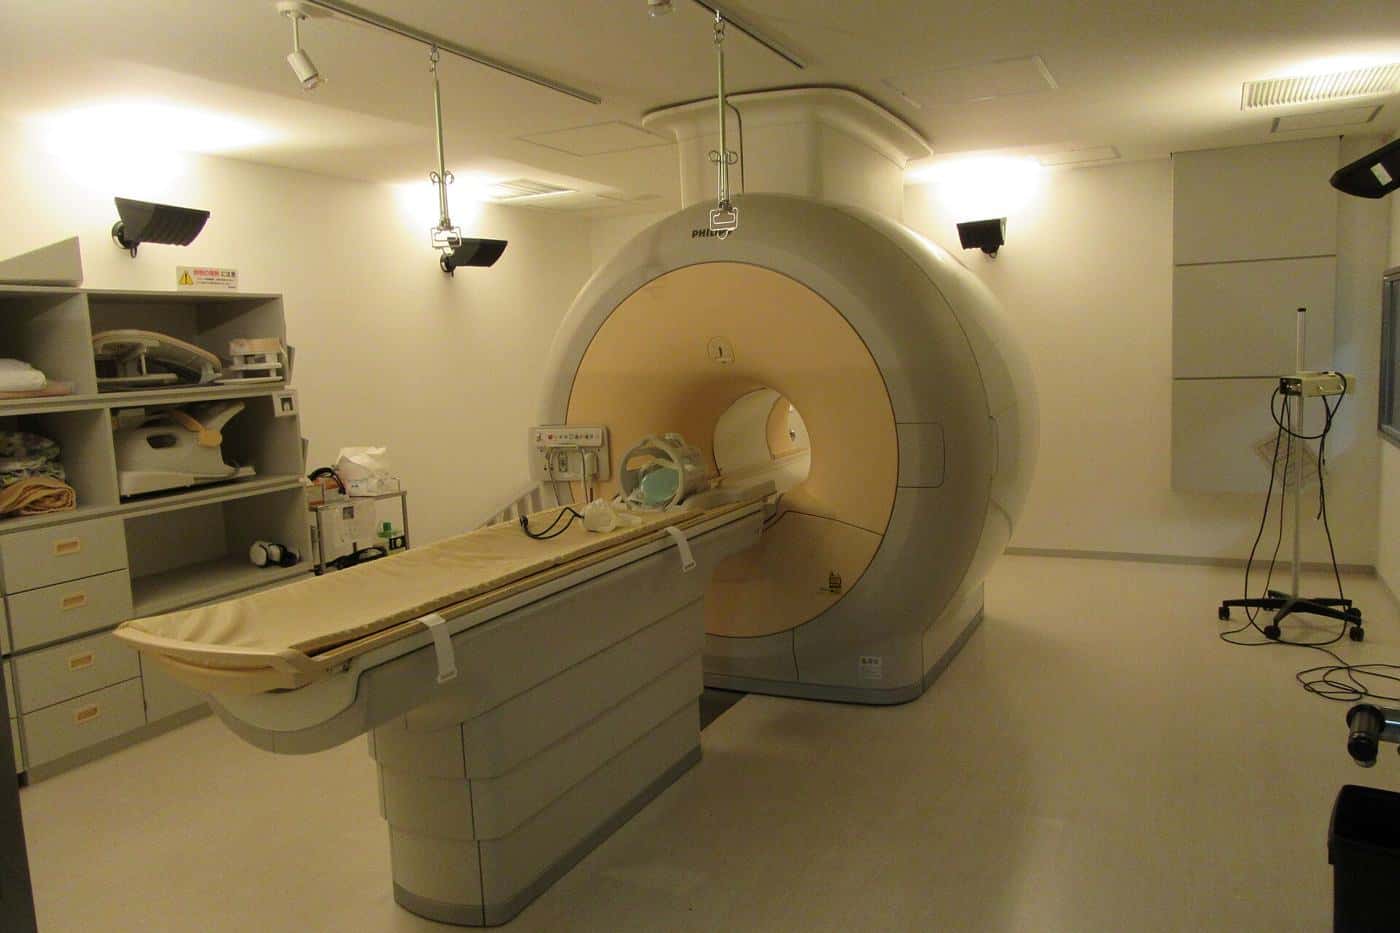
An MRI or a mass spectrometer is too expensive, too sensitive and too mobile for a general property policy. Medical and scientific equipment coverage is written for the specific risks: breakdown, power surges, contamination and transport.
Who buys medical and scientific equipment coverage
Clinics, imaging centers and practices
Outpatient imaging centers, physician groups, dental and veterinary practices with high-value imaging equipment that their property policy does not fully address.
Mobile imaging and diagnostic services
Companies that move MRI, CT or ultrasound units between hospitals and clinics on a schedule. Transit and set-up at each site are the main exposures.
Labs, universities and equipment lessors
Research labs and testing facilities with analyzers and instruments, and lessors who place equipment at customer sites and need their interest protected.
Request a quote
There is no separate application for this class, so start with the short inland marine quote request. Someone will follow up with any underwriting questions specific to your risk. Insurance agents can also request an appointment.
Equipment commonly insured
- MRI, CT, X-ray, ultrasound and mammography units
- Mobile imaging coaches and portable diagnostic devices
- Laboratory analyzers, microscopes and research instruments
- Dental and veterinary imaging equipment
- Equipment leased to hospitals and clinics
Coverage features
- All-risk physical damage, including mechanical and electrical breakdown
- Transit and installation
- Business income or extra expense while equipment is down
- Coverage for leased equipment with the lessor as loss payee
Losses that drive claims
Electrical surges and power quality problems can damage imaging electronics. Water leaks, sprinkler discharge and HVAC failures affect equipment rooms and labs. Mobile units face road accidents and damage during set-up. Ultrasound probes and portable devices are dropped. For MRI units, a magnet quench, where the magnet loses its superconducting state and releases helium, can mean costly helium replacement and downtime. Ask whether quench and helium replacement are covered, and under what conditions.
What underwriters ask
- Make, model, year and serial number of each major unit, with replacement cost
- Whether units are fixed, mobile or moved between sites
- Power conditioning, surge protection and backup power
- Service contract details and who performs maintenance
- Lessor or lender loss payee requirements
Exclusions and gaps
Wear, gradual deterioration and failures covered by the manufacturer's warranty or service contract are often excluded. Damage from software errors, data corruption or cyber events usually sits outside the equipment form. Tubes and other consumable parts may have their own valuation or exclusion. Business income may need a waiting period before it pays, so match it to how long your practice can absorb lost scans.
How to get a quote
- Build a schedule of major units with make, model, year, serial number and replacement cost.
- Note where each unit is kept, and for mobile units, the routes and host sites.
- Describe power protection, cooling, fire suppression and water detection in equipment rooms.
- Attach the service contract summary so coverage can work around it.
- List leased or financed units with the lessor's or lender's loss payee wording.
- Estimate lost revenue or extra expense if a main unit were down for a few weeks.
Common questions
Does a service contract replace insurance?
No. A manufacturer service contract usually covers wear and failures. It does not cover fire, water damage, theft or a dropped probe. Insurance and the service contract work together.
Does my office property policy cover my imaging equipment?
It may cover it as business personal property, but limits, breakdown and electrical damage terms are often a poor fit for high-value diagnostic equipment. Many practices schedule major units on a separate equipment form.
Is a mobile imaging coach covered on the road?
The equipment inside can be covered in transit and at each host site on an inland marine form. The vehicle or trailer itself is usually a commercial auto question.
Are leased units covered if the lease makes me responsible?
You can insure leased equipment you are responsible for, with the lessor named as loss payee. Read the lease to see what value and coverage you have agreed to provide.
Related coverage
EDP & Computers
Servers, laptops, point-of-sale and data processing equipment, plus data restoration.
Coverage & quoteMiscellaneous Floater
For movable business property that doesn't fit any other class, listed item by item.
Coverage & quoteCommunications & Towers
Radio, TV and cell towers, antennas, broadcast and transmission equipment.
Coverage & quoteCommercial Property
Buildings, contents and business income at fixed locations: the partner to your inland marine.
Coverage & application