Oil and gas equipment insurance
Oilfield equipment works in remote locations, moves from lease to lease, and faces fire, blowout and theft. Oil and gas equipment coverage is written on an inland marine form built for those sites.
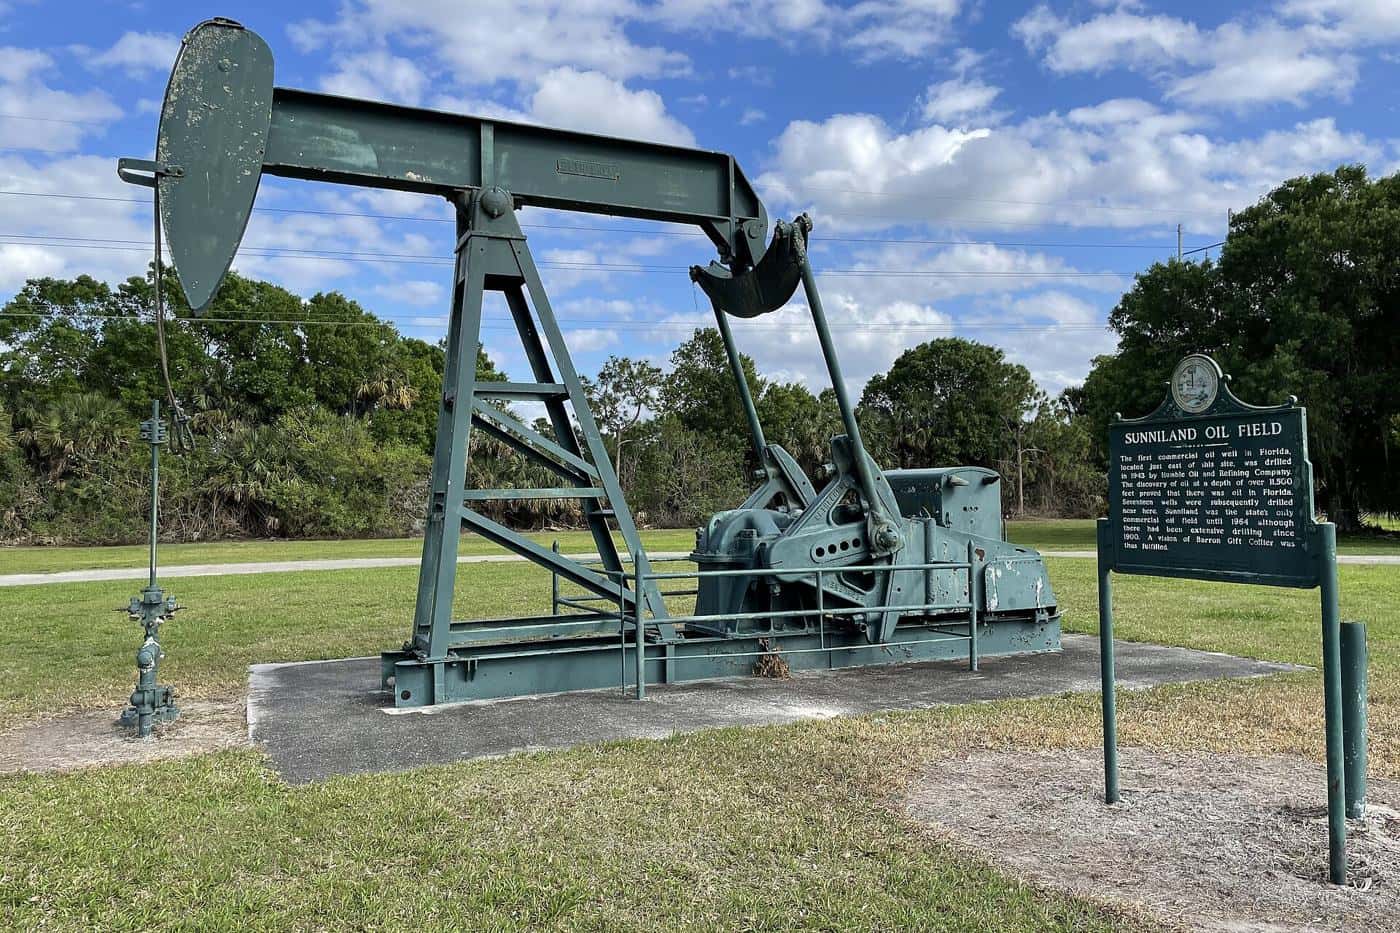
Who buys oil and gas equipment coverage
Operators and lease owners
Companies that own wells and the lease equipment on them: pumping units, tank batteries, separators and flowlines. Their equipment is spread across many remote leases.
Oilfield service contractors
Well servicing, workover, wireline, hot oil, frac and roustabout companies whose rigs and trucks move from job to job. Their exposures look more like contractors equipment, with transit and job site risks.
Equipment rental companies
Companies that rent compressors, tanks, pumps and tools to operators. They need coverage while equipment is out on customer leases.
Request a quote
There is no separate application for this class, so start with the short inland marine quote request. Someone will follow up with any underwriting questions specific to your risk. Insurance agents can also request an appointment.
Equipment commonly insured
- Well servicing and workover rigs
- Pumping units, compressors and separators
- Tank batteries and lease equipment
- Frac, coiled tubing and wireline equipment
- Oilfield service contractors' mobile equipment
Coverage to ask about
- Equipment while in a well or downhole, often excluded or sub-limited
- Fire and explosion at the wellsite
- Theft of copper, tools and portable equipment
- Rented and leased equipment
- Transit between leases
Typical oilfield losses
Fire at a tank battery or wellhead can destroy lease equipment in minutes. Lightning strikes tanks. Rigs overturn while moving between leases on rough roads. Theft of copper, batteries, tools and small engines is common at unattended sites. Flash flooding damages equipment on low-lying pads. A blowout can cause both equipment loss and well control costs, which are a separate type of coverage.
What underwriters ask
- Schedule of equipment with year, make, model, serial number and value
- Type of operation: production, drilling, servicing or rental
- States and basins where you work
- Whether any equipment goes downhole and what it is worth
- Security at yards and leases, and how equipment is stored between jobs
- Loss history for the past three to five years
Gaps to know about
Downhole tools are often excluded or written with a separate limit and a higher deductible. Well control, cost to redrill and seepage or pollution cleanup are not equipment coverage and need their own policy. Mechanical breakdown and wear are usually excluded. Equipment in a well that is lost because of a stuck pipe or fishing job may not be covered unless the policy says so. Rented equipment needs its own limit, and the rental agreement may make you responsible for the full replacement cost.
How to get an oilfield equipment quote
- Build a schedule of rigs, units and tools with year, make, model, serial number and value.
- Separate surface equipment from anything that goes downhole, with values for each.
- List the yards, leases and states where equipment is kept or used.
- Gather rental and master service agreements that set insurance requirements.
- Pull five years of loss runs from your current insurer.
- Note security at yards and how equipment is moved between leases.
Drilling equipment insurance
Drilling rigs, workover rigs, pumps and the trucks and trailers that carry them are some of the most valuable equipment in the oilfield. Drilling equipment insurance covers that equipment above ground: on the lease, in transit between leases and in the yard.
Equipment below the surface is a different exposure. Downhole tools and equipment lost or stuck in a well are often excluded or covered only by a separate endorsement, so ask how a quote treats them.
Common questions
Does oil and gas equipment insurance cover drilling equipment?
It can cover drilling and workover rigs and their support equipment above ground, on the lease and in transit. Downhole tools and equipment in the hole are often excluded or need their own endorsement.
Is downhole equipment covered?
Equipment in the hole is usually excluded unless specifically added, and it is often written with a separate limit and deductible. Ask if it matters to your operation.
Does equipment coverage pay to control a blowout?
No. Well control and redrilling costs are written on a separate control of well policy. The equipment form covers physical damage to the equipment itself.
Do master service agreements affect my coverage?
Yes. MSAs often require specific limits, additional insured status and waivers of subrogation, and they may shift responsibility for equipment loss between the operator and contractor. Share them with your agent.
Is a service rig covered while moving on the highway?
The rig as equipment can be covered in transit on the inland marine form. A rig registered as a vehicle may also need to be on the commercial auto policy, so ask how the two policies divide it.
Related coverage
Equipment Floater
Covers mobile equipment wherever it goes: the yard, the trailer, and every job site in between.
Coverage & applicationCommunications & Towers
Radio, TV and cell towers, antennas, broadcast and transmission equipment.
Coverage & quoteEquipment Rented From Others
Covers machines you rent or lease for a job, so a rental contract loss doesn't come out of pocket.
Coverage & applicationMotor Truck Cargo
Covers the freight on your truck: carriers legal liability, owners cargo and contingent cargo.
Coverage & application