Miscellaneous floater insurance
Some movable property does not belong in any standard class: a mobile kitchen trailer, a bounce house inventory, a set of survey instruments, a farmer's market canopy. A miscellaneous floater schedules it item by item.
Examples
- Vending machines and kiosks placed at other locations
- Musical instruments and sound equipment
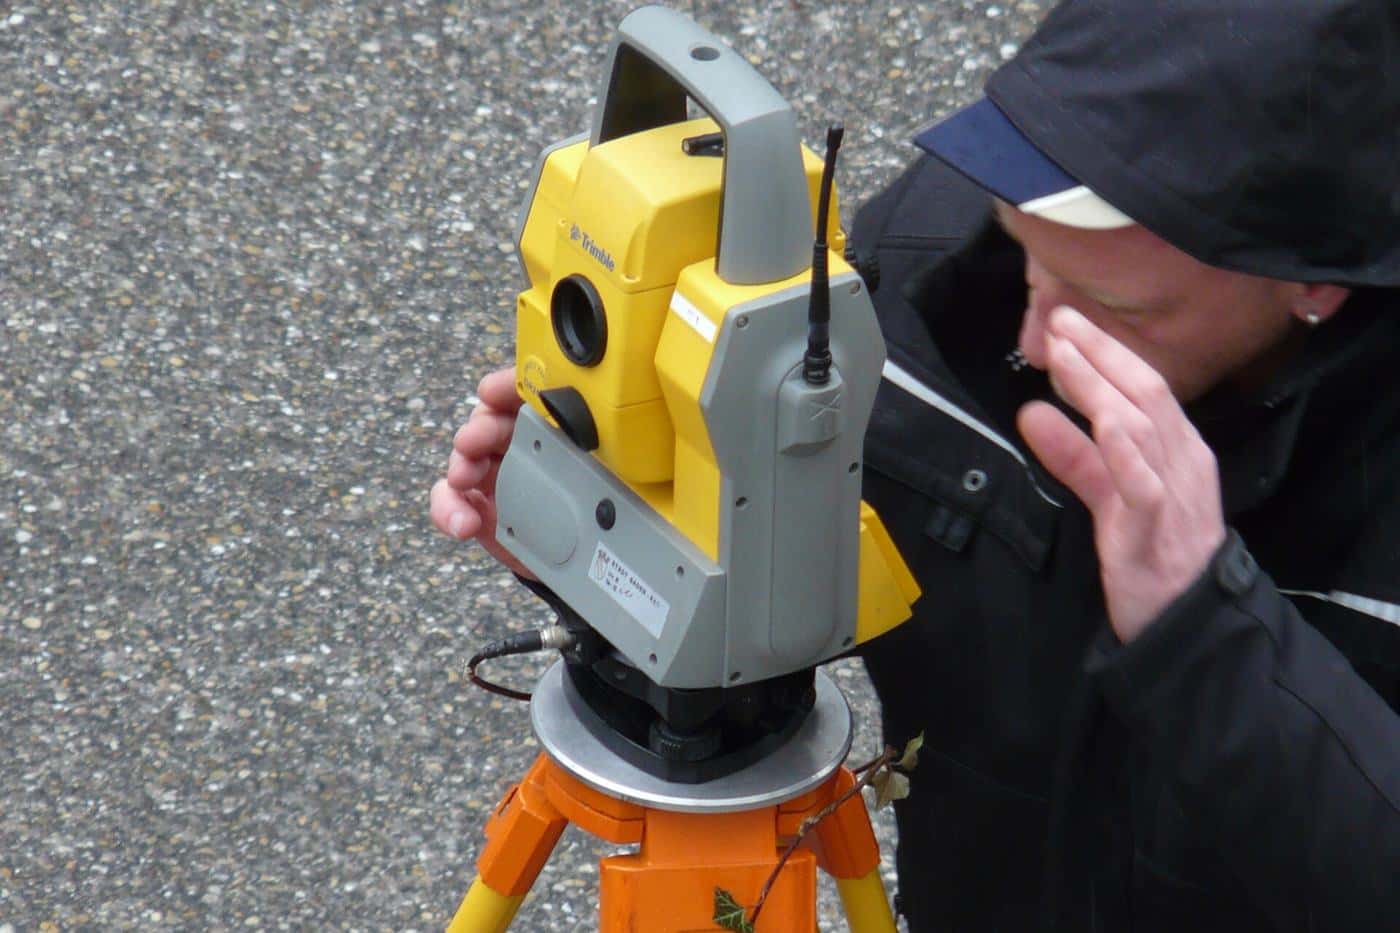
- Survey and engineering instruments
- Mobile kitchen equipment and catering gear
- Rental inventory such as tents, tables and party equipment
- Signs, displays and point-of-purchase fixtures
Request a quote
There is no separate application for this class, so start with the short inland marine quote request. Someone will follow up with any underwriting questions specific to your risk. Insurance agents can also request an appointment.
How it works
Each item, or each group of similar items, is listed with a value. Coverage follows the property anywhere within the policy territory. Most forms are open-perils, subject to standard exclusions such as wear and tear, breakdown and unexplained disappearance.
Choosing the policy terms
Scheduled or blanket
High-value items are usually scheduled one by one. A blanket limit with a per-item maximum can cover groups of small items, such as a party rental company's tables and chairs, without listing each one.
Replacement cost or actual cash value
Replacement cost pays to buy new, similar property. Actual cash value subtracts depreciation. Older gear is often written at actual cash value, so ask which applies to each item.
Coinsurance
Some floaters include a coinsurance clause that reduces a claim if you insured the property for less than a set percentage of its value. Keep the schedule current, especially after you buy new items.
Who buys a miscellaneous floater
Small businesses with valuable property that leaves the building: party and event rental companies, vending operators, caterers, musicians, surveyors, sign companies and market vendors. It also suits businesses whose main policy has a low limit for property away from premises. If the property is mostly contractors' tools and machinery, an equipment floater is usually a better fit. If it is computers, cameras or medical devices, a specialty form may offer better terms.
What underwriters ask
- A list of items with description, serial number where available, and value
- Where the property is kept overnight and where it is used
- How it is transported, and whether it is left in vehicles or trailers
- Whether any items are rented or lent to customers
- Security at your storage location
- Losses in the past three to five years
Gaps to ask about
Theft from an unattended vehicle is often covered only if the vehicle was locked and there are signs of forced entry. Mysterious disappearance, where an item is simply missing with no evidence of theft, is a common exclusion. Property rented to customers may be excluded unless the policy is written for rental inventory. Flood and earthquake may be excluded or sub-limited. Mechanical breakdown of equipment like vending machines is usually not covered.
How to schedule property on a floater
- Walk through what you own that leaves your building and write down each item or group of items.
- Record the description, make, model, serial number and purchase date where you have them.
- Assign a value to each item, using recent receipts or current replacement prices.
- Note where each item is stored, used and transported.
- Decide what to schedule individually and what can go under a blanket limit.
- Update the schedule when you buy, sell or retire items, not just at renewal.
Common questions
When should I use a miscellaneous floater instead of property coverage?
When the property moves around or sits at locations you do not control. A building policy covers things at the listed address, while a floater follows them.
Can I add items in the middle of the policy term?
Yes. Most floaters let you add scheduled items by endorsement. Some include automatic coverage for newly acquired property for a limited number of days, so report new items promptly.
Are my items covered if I rent them out?
Not on every form. Some floaters exclude property while rented or loaned to others. If renting is part of your business, ask for a form that covers rental inventory.
Is a miscellaneous floater the same as an equipment floater?
They work the same way, but an equipment floater is built for contractors' tools and machinery. A miscellaneous floater is for movable property that does not fit any other class.
Related coverage
AV & Production Equipment
Cameras, lighting, sound and staging gear for production crews and event companies.
Coverage & quoteEDP & Computers
Servers, laptops, point-of-sale and data processing equipment, plus data restoration.
Coverage & quoteExhibition & Trade Show
Exhibits, displays and loaned works at shows, fairs and traveling exhibitions.
Coverage & quoteEquipment Floater
Covers mobile equipment wherever it goes: the yard, the trailer, and every job site in between.
Coverage & application