EDP insurance for computers and data processing equipment
Business property policies treat computers like furniture. EDP coverage is written for electronics: power surges, overheating, breakdown, laptops that travel, and the cost of restoring lost data.
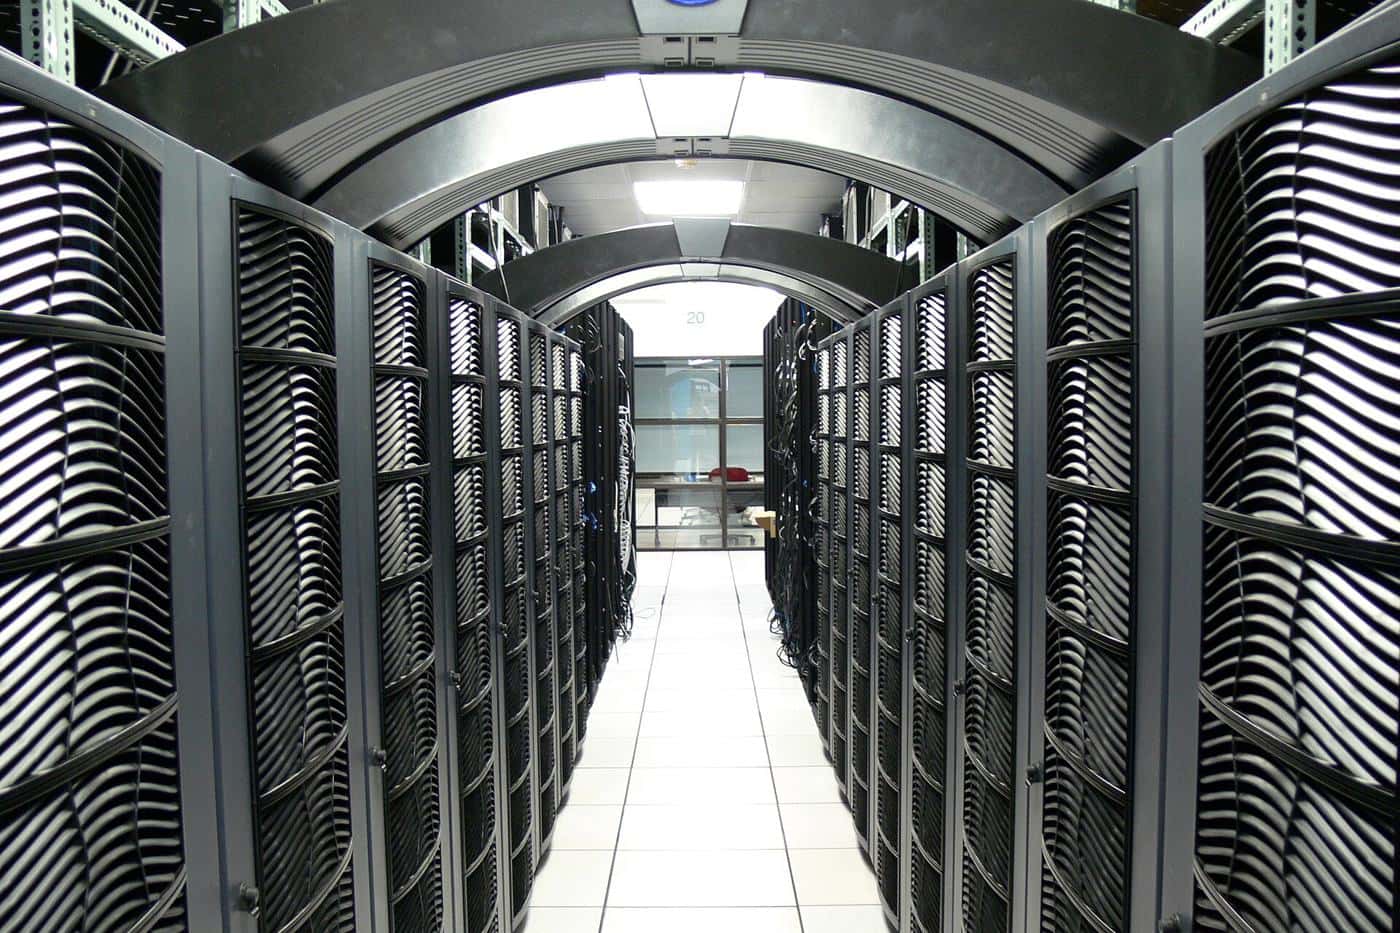
What EDP covers
- Computers, servers, networking equipment and peripherals
- Laptops, tablets and mobile devices away from the office
- Electrical surge, short circuit and mechanical breakdown
- Data and media restoration costs
- Extra expense to keep operating, such as renting replacement equipment
Request a quote
There is no separate application for this class, so start with the short inland marine quote request. Someone will follow up with any underwriting questions specific to your risk. Insurance agents can also request an appointment.
Typical EDP losses
Power surges and electrical damage
A lightning strike nearby or a utility surge can damage servers, switches and workstations at once. Some property policies exclude or limit electrical damage to electronics, which is a main reason to buy EDP.
Overheating and cooling failure
When the air conditioning in a server room fails, equipment can overheat. Ask whether damage from a change in temperature or humidity is covered, since some forms require it to be added.
Laptops and devices on the road
Laptops are stolen from cars, dropped at job sites and left behind at airports. Theft from an unattended vehicle often has conditions, such as the vehicle being locked with the device out of sight.
EDP or cyber
EDP covers physical loss to equipment and media. Cyber insurance covers hacking, ransomware, data breach response and liability. A business that depends on its systems often needs both.
What underwriters ask
- Replacement cost of hardware at each location, plus values of laptops and mobile devices
- Surge protection, uninterruptible power supply and backup generator
- Server room cooling, fire suppression and water detection
- How often data is backed up and where the backup is stored
- Whether equipment is owned, leased or financed
Gaps to ask about
Data restoration coverage usually pays to restore data from backups, not to recreate years of work that was never backed up. Losses from viruses, hacking or programming errors are usually excluded from EDP and belong on a cyber policy. Gradual deterioration, obsolescence and normal wear are excluded. Equipment that is leased may need the lessor added as loss payee. And if the property policy also covers computers, decide which policy is primary so there is no overlap or gap.
How to get an EDP quote
- List hardware by location: servers, network gear, workstations and peripherals, with replacement cost.
- Count laptops, tablets and other portable devices and give a total value.
- Describe surge protection, UPS, cooling and fire suppression in any server or network room.
- Explain your backup routine: how often, what is backed up and where copies are kept.
- Estimate the extra expense of staying open if systems went down for a week.
- Note any leased or financed equipment and the lessor's loss payee wording.
Common questions
Who needs EDP coverage?
Any business that depends on its computer equipment: engineering and design firms, data centers, medical offices, call centers, and contractors running estimating and survey systems.
Does EDP cover ransomware?
Generally no. Ransomware, hacking and viruses are cyber losses. EDP is for physical damage to hardware and media, such as fire, water, surge and theft.
Is EDP coverage written at replacement cost?
Many EDP forms offer replacement cost, sometimes with a functional replacement clause that pays for current equipment of similar capability. Older equipment may be settled at actual cash value, so check the valuation terms.
Are employee laptops at home covered?
Many EDP forms cover company-owned devices anywhere in the policy territory, including employees' homes. Personally owned devices used for work usually are not covered.
Related coverage
Medical, Diagnostic & Scientific
Imaging, lab and diagnostic equipment, fixed or mobile, including breakdown.
Coverage & quoteCommunications & Towers
Radio, TV and cell towers, antennas, broadcast and transmission equipment.
Coverage & quoteMiscellaneous Floater
For movable business property that doesn't fit any other class, listed item by item.
Coverage & quoteAV & Production Equipment
Cameras, lighting, sound and staging gear for production crews and event companies.
Coverage & quote